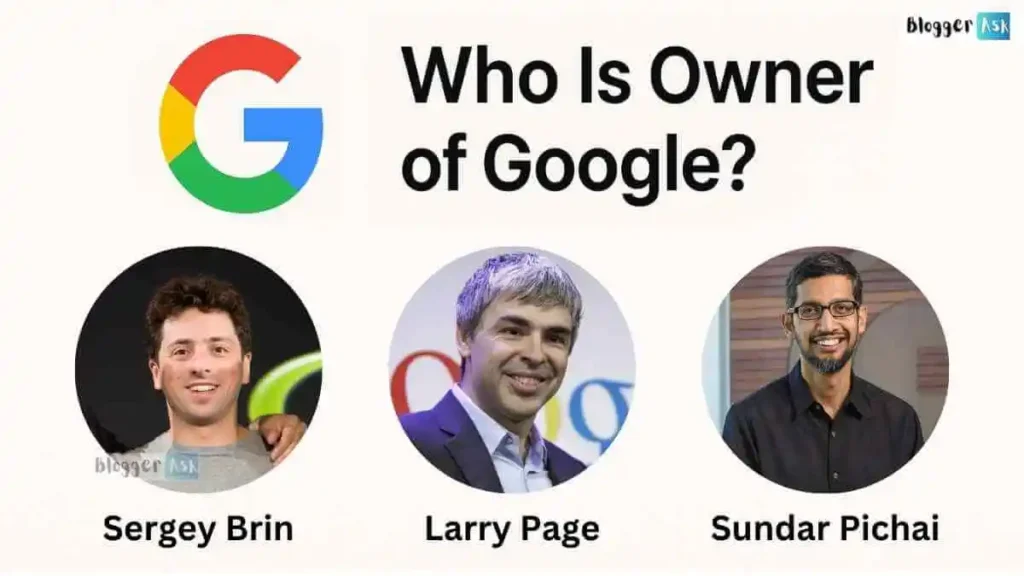
⚡ Quick Answer: Who Owns Google?
Alphabet Inc. owns Google. Specifically, it owns Google LLC through a holding company called XXVI Holdings Inc., which Alphabet set up in 2017 to keep Google legally separate from its other businesses. That much is settled and rarely disputed.
What surprises most people is who actually calls the shots inside Alphabet. Larry Page and Sergey Brin hold a class of stock that carries ten votes per share instead of one. Between them, according to Alphabet’s April 2026 proxy filing with the SEC, that adds up to 52.7% of all voting power — 27.4% for Page and 25.3% for Brin. Add up every other shareholder on the planet, and the two of them still win the vote.
Sundar Pichai, who runs the company day to day, owns 227,560 shares of the ordinary Class A stock. That’s under 1% of the vote. He runs Google, and he’s been paid extremely well for it — but running it and owning it turned out to be two separate things, and only one of them belongs to him.
| Role | Who | What They Actually Control |
|---|---|---|
| Legal owner | Alphabet Inc. (via XXVI Holdings Inc.) | Owns Google LLC outright as a subsidiary |
| Controlling owners | Larry Page (27.4%) + Sergey Brin (25.3%) | 52.7% combined voting power |
| Runs the company | Sundar Pichai | Daily operations; under 1% voting power |
| Largest economic stake | Vanguard Group | ~8.5% of Class A shares, ~3.5% of total votes |
| Everyone else | Public shareholders | Most of the money, almost none of the say |
Source: Alphabet Inc. DEF 14A Proxy Statement, record date April 6, 2026, SEC EDGAR.
The numbers worth knowing before you go further
Alphabet’s market cap has been sitting somewhere between $4.0 and $4.3 trillion through most of 2026, moving with the stock like any large-cap does — it dropped about 7% the day after Q2 earnings came out. That quarter, revenue hit $119.8 billion, up 24% year over year, with Google Cloud alone jumping 82% to $24.8 billion. Google’s core products still carry almost the entire business: Google Services brought in $94.5 billion of that total, while the Other Bets division — Waymo, Verily, and the rest — brought in $382 million and lost $1.8 billion.
Three things happened this year that reshaped what Alphabet actually owns. In March, it closed the largest acquisition in company history: a $32 billion, all-cash purchase of the cloud-security firm Wiz. Court filings from Google’s own antitrust case revealed the company holds roughly 14% of Anthropic, capped at 15%, with zero voting rights. And after SpaceX went public in June, Alphabet’s 13F disclosed a position of 551.2 million shares — about 7.2% of SpaceX’s Class A stock, worth close to $94 billion.
None of that touches who controls Alphabet itself. It just means the company Page and Brin control got a lot bigger this year.
Why “who owns Google” has three different correct answers
There’s a legal answer, a financial answer, and a control answer, and they point in three different directions.
Legally, Alphabet Inc. owns Google LLC outright, through XXVI Holdings Inc. Financially, ownership is scattered across millions of people — pension funds, index funds, and individual investors who hold GOOGL or GOOG and share in whatever Alphabet earns. And in terms of who actually decides what happens, it comes down to two people: Page and Brin, through a class of stock nobody else can buy.
Most write-ups on this topic pick one of those three and call it the whole story. It isn’t. A Vanguard fund can hold more Alphabet stock by dollar value than Larry Page does personally, and still carry a fraction of his influence over the company. That gap is the entire point of how this is structured.

[Figure 1: How ownership flows from public shareholders through Alphabet Inc. down to Google LLC — with voting control held separately by the two founders.]
The document that actually settles the numbers is Alphabet’s DEF 14A — the proxy statement every public company files before its annual shareholder meeting. It lists who owns what, how many votes that represents, what executives are paid, and what’s up for a vote that year. For a company like Alphabet, it’s about as close to a primary source as this topic gets.
Alphabet’s three share classes, and why votes don’t track shares
Alphabet trades under two tickers because it has three separate classes of stock, and only one of them was ever built to carry serious voting weight.
| Share Class | Ticker | Votes Per Share | Who Holds It |
|---|---|---|---|
| Class A | GOOGL | 1 vote | Public investors |
| Class B | Not publicly traded | 10 votes | Page, Brin, and a small group of early insiders, including former CEO Eric Schmidt |
| Class C | GOOG | 0 votes | Public investors, employees paid in stock |
You can’t buy Class B shares through any brokerage at any price. The only people who hold them are the ones who had them before the 2004 IPO, or who received them in an approved transfer from someone who did. As of April 2026, there were roughly 5.82 billion Class A shares outstanding against just 835.8 million Class B shares — a small slice of the total, but one that outvotes everything else ten to one, share for share.
GOOGL and GOOG aren’t different investments in any way that affects your returns. Same company, same dividend, same economic rights. The only difference is that GOOGL carries a vote and GOOG doesn’t, which is why the two usually trade within a dollar or two of each other.
Larry Page and Sergey Brin’s actual stake
Here’s the breakdown, straight from the 2026 proxy:

Figure 2: Why a small block of Class B shares outweighs billions of public Class A and Class C shares.
Here’s the breakdown, straight from the 2026 proxy:
| Shareholder | Class B Shares Held | % of Class B | Total Voting Power |
|---|---|---|---|
| Larry Page | 389,051,160 | 46.5% | 27.4% |
| Sergey Brin | 358,939,978 | 42.9% | 25.3% |
| Combined | 747,991,138 | 89.4% | 52.7% |
52.7% is a majority on its own — no coalition of other shareholders can override it. Page and Brin, meanwhile, own only about 3% of Alphabet each by dollar value — a small fraction of the company, controlling the majority of its votes.
Picture the annual shareholder vote as 100 total votes in the room. Vanguard shows up with about 3.5 of them. BlackRock brings roughly 2.5. Every other investor on earth splits most of what’s left. Then Page walks in holding 27, Brin holding 25. That’s 52 between the two of them, more than everyone else combined.
There’s no signed agreement forcing them to vote the same way — nothing in Alphabet’s filings binds them together. They’ve simply voted in lockstep since the IPO, which is why every analysis of this company, including this one, treats their stakes as a single controlling bloc.
You’ll sometimes see this percentage quoted differently elsewhere — 56%, 51.4%, numbers close but not identical. That’s usually not an error. Voting power shifts slightly every quarter as buybacks retire Class A shares and employees vest into new ones, so a source citing an older filing will land on a slightly different number. 52.7% is what Alphabet itself reported as current, as of its most recent proxy.
Who sits on Alphabet’s board
The board is where that 52.7% actually gets exercised — it’s a ten-person group that meets several times a year and, since October 2025, includes a dedicated committee for risk and regulatory compliance.
| Director | Role |
|---|---|
| John L. Hennessy | Independent Chair; former Stanford University president |
| Larry Page | Co-founder, controlling shareholder |
| Sergey Brin | Co-founder, controlling shareholder |
| Sundar Pichai | CEO |
| Frances H. Arnold | Independent Director |
| R. Martin “Marty” Chávez | Independent Director |
| L. John Doerr | Independent Director; early investor, holds a small Class B stake of his own |
| Roger W. Ferguson Jr. | Independent Director |
| K. Ram Shriram | Independent Director; early investor |
| Robin L. Washington | Independent Director |
Two names on that list connect back to earlier chapters of the company. Shriram is the one who introduced Jeff Bezos to Page and Brin in 1998, setting up the investment story later in this article. Schmidt, meanwhile, who shows up as a Class B holder in the share-class table above rather than on today’s board, ran Google as CEO from 2001 to 2011 and stayed on as Alphabet’s Executive Chairman until 2018 — he kept his voting shares after stepping back from the day job.
Between them, the full slate of Alphabet’s directors and officers controls about 92% of all Class B stock and roughly 54% of the total vote, a touch higher than Page and Brin’s individual figure since a few other directors hold small Class B positions of their own.
Sundar Pichai: running it isn’t owning it
Pichai became CEO of Google LLC in 2015, then of Alphabet itself in 2019. His stake, per the 2026 proxy, comes to 227,560 Class A shares plus roughly 1.6 million non-voting Class C shares held directly, with more spread across family trusts. Zero Class B shares.
His base salary runs $2 million a year, and his RSU compensation has made him wealthy — worth well into nine figures at current prices. If Page and Brin ever decided his direction was wrong for the company, they could still replace him through the board, and no other shareholder’s vote would need to be involved.
People sometimes assume Google’s CEO sits in the same financial tier as its founders. He doesn’t, not remotely. Page and Brin’s net worth has been estimated by Forbes and Bloomberg somewhere between $270 and $330 billion apiece at various points in 2026, depending on the tracker and the day — territory that puts them among the two or three richest people alive. That’s founder-level equity built up over two decades, not an executive’s compensation package, however generous.
The index funds that hold the most stock but have the least say
Strip out the founders, and the largest owners of Alphabet by dollar value aren’t people at all. Vanguard holds roughly 493.8 million Class A shares — about 8.5% of that class — which translates to only around 3.5% of the actual vote. BlackRock’s position runs about 356.9 million shares, close to 6% of Class A, worth around 2.5% of total voting power.
Vanguard’s number shifted slightly in the filings this year for a technical reason: in March 2026, it told the SEC that an internal reorganization ended its practice of reporting all its funds’ holdings as one aggregated figure, so several of its affiliated entities now file separately. That’s part of why different sources sometimes show slightly different Vanguard percentages.
The practical upshot doesn’t change: even if Vanguard, BlackRock, Fidelity, and State Street pooled every vote they hold, they’d still fall well short of Page and Brin’s majority. Passive index funds simply aren’t built to fight for board seats — and structurally, in Alphabet’s case, they couldn’t win that fight anyway.
Google LLC versus Alphabet Inc.: public, private, and everything between
Google LLC has never traded on any exchange. Alphabet Inc. is the public company, listed on Nasdaq under GOOGL for Class A and GOOG for Class C, and it’s Alphabet — not Google — that anyone actually buys when they say they bought “Google stock.”
That distinction matters more than it sounds. Google LLC generates the overwhelming majority of Alphabet’s revenue, so buying GOOGL is, economically, a bet on Google’s performance. Legally, though, you own equity in a holding company several layers removed from Google itself, with none of the direct claim an actual owner of Google LLC would have, because that entity was never for sale.
What’s actually inside Alphabet — XXVI Holdings, Wiz, Anthropic, SpaceX
“Who owns Google” increasingly points outward too — toward what Google itself owns, and what Alphabet owns through it. That picture has gotten a lot more interesting in 2026.
Alphabet doesn’t hold Google LLC directly. It owns Google through XXVI Holdings Inc., an intermediate company created in 2017 specifically so Google’s core business could sit on equal legal footing with Waymo, Verily, and the rest of the Other Bets, rather than having those units technically nested inside Google itself. The name is a small joke: XXVI is Roman numerals for 26, the number of letters in the alphabet.
Below that sits the business most people recognize:
| Product / Business | Held Under | What It Does |
|---|---|---|
| Search, Ads, Gmail, Maps | Google LLC | Core advertising and consumer products |
| YouTube | Google LLC | Video platform, acquired for $1.65 billion in 2006 |
| Android, Chrome, Play Store | Google LLC | Mobile OS, browser, app marketplace |
| Google Cloud | Google LLC | Enterprise cloud and AI infrastructure |
| Google DeepMind | Google LLC | Builds the Gemini model family |
| Waymo, Verily, Wing, Isomorphic Labs | Alphabet Inc. directly | Self-driving cars, health tech, drone delivery, AI drug discovery |
Then there’s what Alphabet has bought and invested in over just the past eighteen months, which is where a lot of competing “who owns Google” content stops being current.
Wiz is the clean case: Google simply bought it. The cloud-security company turned down $23 billion in 2024, came back around to a $32 billion all-cash offer, and after roughly a year clearing antitrust review across multiple countries, the deal closed on March 11, 2026 — the largest purchase in Google’s history by a wide margin. Wiz now operates inside Google Cloud, brand intact.
Anthropic and SpaceX are different animals — Alphabet owns pieces of both without controlling either. Google’s Anthropic position, roughly 14% and capped at 15% by agreement, came to light through documents filed in Google’s own antitrust litigation rather than through any announcement; it carries no board seat and no voting rights.
A newer commitment on top of that — up to $40 billion, starting with $10 billion in cash — values Anthropic at $350 billion, with the remaining $30 billion tied to performance targets. The SpaceX stake surfaced differently: once SpaceX went public in June 2026, Alphabet’s next 13F filing was legally required to disclose it, revealing 551,189,500 shares, about 7.2% of SpaceX’s Class A stock and worth close to $94 billion at the time.
It’s the same gap that separates Vanguard’s stake in Alphabet from Page’s — a large position with zero vote sits worlds apart from a controlling one. Whatever Alphabet does with Wiz, Anthropic, or SpaceX, it changes Alphabet’s balance sheet. It doesn’t change who runs Alphabet.
How the ownership structure got built, 1998 to now
| Year | Event | Ownership Impact |
|---|---|---|
| 1998 | Google Inc. incorporated; $100,000 seed check from Andy Bechtolsheim | Page and Brin sole owners |
| 1998 | Jeff Bezos invests $250,000 in a follow-on round | Early outside investor |
| 1999 | Sequoia Capital and Kleiner Perkins invest ~$25 million | First major dilution; founders keep control |
| 2004 | IPO at $85/share; dual-class structure written into the prospectus | Public gets economics; founders keep the vote |
| 2005–2008 | Android and DoubleClick acquired | Early building blocks of Google LLC |
| 2014 | Class C shares introduced via stock split | More capital raised without diluting founder votes |
| 2015 | Alphabet Inc. created as holding company | Structure changed; control didn’t |
| 2017 | XXVI Holdings Inc. formed | Google legally separated from Other Bets |
| 2019 | Pichai becomes CEO of Alphabet | Operations handed off; control stays with founders |
| 2026 | Wiz closes, Anthropic and SpaceX stakes disclosed, market cap crosses $4 trillion | Portfolio grows; founder voting power unchanged |
Buried in that timeline is a story most ownership explainers skip entirely. In 1998, Jeff Bezos personally put $250,000 into a $1 million funding round for Google — a bet that cost him roughly four cents a share. By IPO day in 2004, that had grown into about 3.3 million shares, worth over $280 million before the market even closed. Whether Bezos still holds any of it today has never been made public, and there’s no rule requiring him to say.
Could this ever change?
Not through money, and not easily through anything else.
Buying control outright is off the table for two independent reasons. Alphabet’s market cap runs well into the trillions, which puts a controlling economic stake beyond any individual’s reach even before you factor in the structure. And a buyer could only ever buy Class A or Class C stock on the open market, however much cash they had — Class B, the only class that actually carries control, simply isn’t listed anywhere at any price. That’s not an accident; it was built into the 2004 prospectus specifically to make a hostile takeover structurally impossible, not just unlikely.
The one real lever that could shift things is a voluntary sale. Under Alphabet’s charter, any Class B share that gets sold or transferred to someone not pre-approved to hold that class converts automatically and permanently into an ordinary Class A share, losing nine of its ten votes in the process.
Based on how that conversion mechanism is written into the charter, something similar would likely apply if a founder died without heirs pre-approved to hold Class B status — though that scenario has never actually played out, so exactly how it would unfold isn’t fully confirmed. If it worked the way the sale-triggered conversion does, voting control would shift back toward the broader shareholder base for the first time since the IPO.
What Alphabet’s charter doesn’t include is a built-in expiration date. A number of newer dual-class IPOs write in a sunset clause — a fixed number of years after which super-voting shares convert automatically, no sale required. Alphabet has no such provision. Barring a sale or a death without approved heirs, this arrangement simply doesn’t expire.
If anything, the founders’ grip tends to tighten rather than loosen over time, because buybacks shrink the public float of Class A and Class C shares while the fixed pool of Class B stays exactly where it is — nudging the voting percentage up slightly, quarter after quarter. Alphabet paused its buyback program in Q2 2026 to help fund the AI buildout and the Wiz and Anthropic commitments, but the longer pattern has been steady repurchases. For anyone tracking this closely, a large, sudden Class B sale by either founder — visible in SEC Form 4 filings — would be the single clearest signal that the structure is actually shifting.
Do the antitrust cases in the US and EU affect ownership?
No, and this holds across every case currently in progress. Courts and regulators can force Google to change what it’s allowed to do. None of them have any authority over who holds Alphabet’s shares.
The U.S. search-monopoly case has moved fast. Judge Amit Mehta ruled in August 2024 that Google illegally maintained a monopoly in general search, then handed down remedies in September 2025 — no Chrome or Android breakup, but a ban on exclusive distribution deals and an order to share certain search data with qualified competitors.
A final judgment followed on December 5, 2025, and Google filed its notice of appeal on January 16, 2026, along with a request to stay the data-sharing requirement while that appeal plays out. The DOJ and a group of state attorneys general cross-appealed in February, pushing for the Chrome divestiture Mehta had rejected.
Google’s opening brief went to the D.C. Circuit on May 22, the DOJ answered on July 28, and oral argument is expected sometime between late 2026 and early 2027 — with Google now arguing that AI rivals like OpenAI and Perplexity shouldn’t get access to its mandated data, since neither existed when the case was filed. A final resolution, possibly at the Supreme Court, may not land before 2028.
A separate case, over Google’s advertising-technology business, played out in front of Judge Leonie Brinkema in Virginia. She found Google liable for illegal monopolization back in April 2025, and on September 2, 2026, issued her remedies ruling — a partial win for the company. She declined to force a breakup of Google’s ad exchange, opting instead for six years of behavioral restrictions plus an internal compliance monitor, with the full opinion made public on September 16. Google says it disagrees with the underlying finding and plans to appeal.
Europe hasn’t let up either. On July 2, the EU’s top court closed out an eight-year fight by making a €4.1 billion Android fine final, with no further appeal available. Three weeks later, the European Commission added a combined €890 million penalty under the Digital Markets Act — split between self-preferencing in search results and restrictions on how Play Store developers can steer users elsewhere.
Even in the worst realistic outcome — a court-ordered Chrome divestiture, say — the decision about how to carry that out would still go through Alphabet’s board, and that board answers to Page and Brin’s majority vote. Regulators can rewrite what a company does. Reassigning who holds its shares isn’t something any of them have the power to order.
Why Alphabet never moved to one-share-one-vote
Page and Brin explained their reasoning before Alphabet ever sold a single share to the public. In the letter that accompanied the 2004 IPO prospectus, they argued that public markets push companies toward short-term thinking, and that they wanted room to make long, expensive bets without clearing them with shareholders first.
Twenty-two years later, that argument looks less like founder posturing and more like a description of exactly what’s happening. Alphabet is guiding to $195–205 billion in capital spending this year, on top of the Wiz purchase and tens of billions committed to Anthropic — enough that quarterly free cash flow turned negative for the first time in roughly two decades. A management team answering to a fragmented, one-vote-per-share shareholder base might struggle to greenlight spending at that scale. Page and Brin’s board doesn’t have to.
| Company | Founder Control | Super-Vote Ratio | Can Founders Be Outvoted? |
|---|---|---|---|
| Alphabet (Google) | Page + Brin, 52.7% of votes | 10:1 (Class B) | No |
| Meta | Zuckerberg, majority control | 10:1 (Class B) | No |
| Snap | Spiegel + Murphy | 10:1 (Class C) | No — public gets 0 votes |
| Amazon | Jassy (CEO, not a founder) | 1:1 | Yes |
| Apple | No founder control remains | 1:1 | Yes |
Proxy advisors like ISS and Glass Lewis tend to treat structures like this as a governance risk across the market generally, on the grounds that shareholders have no real way to hold leadership accountable. The counterargument — that founder control buys the freedom to think in decades instead of quarters — has plenty of supporters among governance researchers too. Neither side has settled the debate, and this article isn’t going to either.
What you get, and don’t get, as a shareholder
Buying GOOGL or GOOG gets you a share of Alphabet’s earnings, eligibility for the 22-cent quarterly dividend, and a vote at the annual meeting.
What it doesn’t get you is much of a chance that your vote changes anything contested. This year’s proxy included shareholder proposals on climate disclosure and AI oversight; the board recommended against all of them, and with Page and Brin holding 52.7% of the vote, none had a realistic path to passing regardless of how anyone else felt. You also don’t get access to Class B stock at any price, and you don’t get direct ownership of Google itself — what you hold is equity in Alphabet, several corporate layers removed.
Questions people ask
Does Google own Anthropic?
No, not in any controlling sense. Google’s stake sits around 14%, capped at 15%, with no board seat and no vote. Anthropic runs independently and also has deep ties to Amazon, which has put in billions of its own.
Does Google own SpaceX?
No — it’s a financial position, not a controlling one. Alphabet’s 551.2 million shares work out to roughly 7.2% of SpaceX’s Class A stock. Elon Musk holds the largest individual stake by far.
What’s the biggest acquisition Google has ever made?
Wiz, bought outright for $32 billion in cash, closing in March 2026. It’s more than double the size of Google’s previous record, the $12.5 billion Motorola Mobility deal from 2012.
Could the antitrust rulings eventually force Page or Brin to sell their shares?
No mechanism in either case gets anywhere near that. Courts can order changes to how Google operates — data sharing, contract terms, in a severe case a forced divestiture — but none of that reaches who holds Alphabet’s stock.
Is there any time limit on the founders’ control?
No sunset clause exists in Alphabet’s charter. The structure holds until a sale or a founder’s death without approved heirs — no fixed end date is built in.
Why does Alphabet still use two different tickers for essentially the same stock?
GOOGL (Class A) carries a vote; GOOG (Class C) doesn’t. Otherwise they’re economically identical, which is why the price rarely diverges by much.
Who actually sits above Google LLC on paper?
XXVI Holdings Inc., an intermediate company Alphabet created in 2017 to put Google on the same legal footing as Waymo, Verily, and its other ventures.
Where this leaves things
Ask who owns Google and the honest answer depends on what you mean by “own.” Alphabet holds the title, through XXVI Holdings. Millions of shareholders hold the financial upside. Page and Brin hold the vote that actually decides what happens next — including how the company spends on bets like Wiz, Anthropic, and SpaceX.
Pichai runs all of it competently, day after day. But running Google and owning it have never been the same job, and nothing in Alphabet’s own filings suggests that changes anytime soon, not while Page and Brin keep their shares.
📖 Continue Reading:
- Who Founded Google?
- Who Is the CEO of Google?
- Companies Owned by Google in 2026
- How Does Google Make Money?
Sources & References
- Alphabet Inc., 2026 Definitive Proxy Statement (DEF 14A), record date April 6, 2026 — SEC EDGAR
- Alphabet Inc., Q2 2026 Earnings Release (Form 8-K exhibit) — SEC EDGAR
- Alphabet Inc. Investor Relations, Q2 2026 Earnings Call materials
- Alphabet Inc., Form 8-K, 2026 Annual Meeting voting results — SEC EDGAR
- Alphabet Inc., Form 10-K, Fiscal Year 2025 — SEC EDGAR
- Alphabet Inc., Form 13F, Q2 2026 — SEC EDGAR
- United States v. Google LLC, Case No. 1:20-cv-03010-APM, U.S. District Court for the District of Columbia
- United States v. Google LLC, Case No. 1:23-cv-108, U.S. District Court for the Eastern District of Virginia (Memorandum Opinion, September 2, 2026)
- U.S. Department of Justice, Office of Public Affairs
- European Commission, Press Release IP/26/1670, July 23, 2026
- Court of Justice of the European Union, Case C-738/22 P, Google and Alphabet v. Commission (July 2, 2026)
- Alphabet Inc. Investor Relations — abc.xyz
Disclaimer:
This article is for informational and educational purposes only and should not be considered financial, investment, legal, or tax advice. Ownership figures, voting percentages, market values, corporate structures, acquisitions, and regulatory developments can change over time. Information is based on publicly available company filings, regulatory records, court documents, and other sources available as of the date of the latest update. Readers should consult primary sources and qualified professionals before making investment or other financial decisions.
Olivia Isabel is a Business & Technology Writer specializing in corporate ownership, company leadership, shareholders, acquisitions, and the business strategies behind major global companies. Her work covers technology, artificial intelligence, social media, finance, e-commerce, automotive, and consumer technology, with a particular focus on explaining who owns, controls, and leads well-known companies.
With a background in Economics and Journalism, Olivia approaches each topic as a research-driven business story. She examines company filings, investor-relations materials, regulatory records, official corporate announcements, and reputable financial sources to distinguish between legal ownership, economic ownership, voting control, and day-to-day management.
Her articles explore the founders behind major companies, current CEOs, significant shareholders, parent companies, subsidiaries, acquisitions, and changes in corporate structure. She has written about companies including Google, Alphabet, Apple, Microsoft, Amazon, Meta, OpenAI, Tesla, SpaceX, YouTube, Instagram, TikTok, WhatsApp, Reddit, Spotify, and other major technology and consumer brands.
Olivia’s goal is to make complicated corporate and financial information clear, accurate, and useful for everyday readers. She is particularly interested in corporate strategy, technology business models, entrepreneurship, emerging AI companies, public markets, and the evolution of globally recognized brands.