⚡ Quick Answer: 50/30/20 vs 70/20/10: Which Budget Rule Is Better?
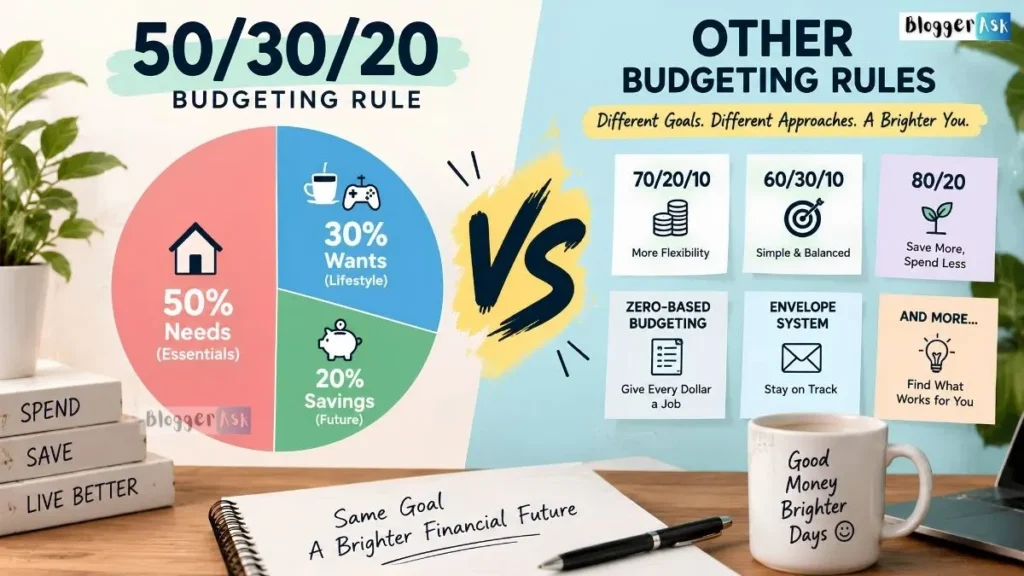
The most common comparison is 50/30/20 vs 70/20/10, and the two rules actually put the same amount toward savings — 20% either way. The real difference is how the other 80% gets divided: 50/30/20 splits it into needs and wants, while 70/20/10 lumps all spending into one bucket and adds a dedicated debt or giving category. A few other named rules exist too (30/30/40, 80/20, 60/40, zero-based budgeting), and which one fits depends less on which is “correct” and more on your actual living costs and how much category-tracking you want to do.
Key takeaways:
- 50/30/20 and 70/20/10 allocate the exact same 20% to savings — the real difference is only in how the remaining 80% is organized.
- At median U.S. income, 70/20/10’s 70% living-expenses target lines up almost exactly with real needs spending, while 50/30/20’s 50% needs cap typically falls about 40% short.
- Neither rule is objectively better; the right one depends on whether you want visibility into needs-vs-wants spending (50/30/20) or a simpler single spending bucket (70/20/10).
50/30/20 vs 70/20/10: The Most Common Comparison
Both rules split your after-tax income into three parts, but they draw the lines in different places. 50/30/20 separates spending into needs (50%) and wants (30%) before setting aside 20% for savings and extra debt payments. 70/20/10 doesn’t separate needs from wants at all — it groups all spending into one 70% “living expenses” bucket, sets aside 20% for savings, and carves out a separate 10% specifically for debt repayment or giving.
What Changes Between the Two Rules
| 50/30/20 | 70/20/10 | |
|---|---|---|
| Spending categories | Two (needs, wants) | One (living expenses) |
| Debt handling | Folded into the 20% savings/debt category | A dedicated 10% category |
| Tracking effort | Higher — requires sorting every expense into needs or wants | Lower — one spending total to watch |
| Savings allocation | 20% | 20% |
Same Income, Two Ways to Split It
To make this concrete, here’s how both rules divide the same income. We’re using $3,762 a month — the after-tax income of a median full-time U.S. worker, based on Bureau of Labor Statistics wage data, using the same income definition (after taxes, before other voluntary payroll deductions) established throughout this site’s 50/30/20 guide.

| Category | 50/30/20 | 70/20/10 |
|---|---|---|
| Needs / Living expenses | $1,881 (50%) | $2,633 (70%) |
| Wants / Debt & giving | $1,129 (30%) | $376 (10%) |
| Savings | $752 (20%) | $752 (20%) |
| Total | $3,762 | $3,762 |
The savings figure is exactly the same under both rules, because both allocate 20% to it. The only real difference is how the remaining 80% gets organized — as two categories you have to sort spending into, or one category you don’t.
Where Each Rule Tends to Break Down
This site’s own analysis of [whether the 50/30/20 rule is realistic] found that real needs spending for a median earner — rent, utilities, groceries, transportation, and insurance — comes to roughly $2,637 a month. Compare that to each rule’s target: 50/30/20’s needs target here is $1,881, meaning real spending runs about 40% over target. 70/20/10’s living-expenses target is $2,633 — just $4 off from the real number.
That’s not a coincidence worth reading too much into on its own, but it does explain why 70/20/10 tends to feel more forgiving at median income levels: its single spending category is sized closer to what people actually spend, while 50/30/20’s 50% needs cap is often unrealistic before you even get to the wants category.
Neither rule “breaks” for the same reason, though. 50/30/20 breaks down when needs genuinely can’t fit under 50%, no matter how the budget is organized. 70/20/10 breaks down differently — because it doesn’t separate needs from wants, it’s possible to hit your 70% target while your actual essential costs and your actual discretionary spending are both individually out of balance, and the rule won’t tell you which one is the problem.
Which Rule Fits Your Situation?
Neither rule is universally better. Which one fits depends on what’s actually driving your budget.
If You Have High Housing Costs or Live in an Expensive Area
70/20/10 tends to fit better here. Its 70% living-expenses target has more room to absorb a high but unavoidable housing cost without forcing you to prove every dollar is “necessary” the way 50/30/20’s needs-versus-wants split does.
If You’re Paying Off Debt Aggressively
70/20/10’s dedicated 10% debt category gives you a clear, separate number to track. If you’re debt-free, that same 10% can shift straight into savings, effectively turning the rule into 70/30.
If You Have Irregular or Variable Income
Both rules struggle equally here, since both assume a fixed monthly figure. If your income varies, the fix isn’t switching rules — it’s averaging your income over three to six months before applying either one, as covered in [how to calculate the 50/30/20 rule].
If You Just Want One Number to Track
70/20/10 wins on simplicity. One spending bucket is easier to glance at than two, especially if sorting expenses into “need” or “want” every time is the part of budgeting you find most tedious.
Other Budgeting Rules Worth Knowing About
50/30/20 and 70/20/10 are the two most commonly compared, but they’re not the only named options.
The 30/30/40 Rule (and Why People Search for “40/30/30”)
The 30/30/40 rule allocates 30% to housing specifically, 30% to other necessary living costs, and 40% to savings and discretionary spending combined — a structure named directly by WalletHub’s coverage of alternative budgeting rules. If you’ve seen it referred to as “40/30/30,” that’s likely the same rule with the numbers reordered from memory — worth double-checking which specific split a source means, since the category order changes what each percentage refers to.
The 80/20 Rule
The simplest of the group: 20% goes to savings, and the remaining 80% covers everything else with no further categorization. It’s essentially 70/20/10 without the separate debt category.
The 60/40 Rule
Splits income into 60% for committed expenses — necessities plus recurring commitments like a gym membership or a streaming subscription you’ve decided to keep — and 40% for everything else. Contrary to how this is sometimes simplified, most common versions of the 60/40 rule do protect savings specifically, often splitting that 40% into further sub-categories like retirement, short-term savings, and discretionary spending rather than leaving savings unprotected.
Zero-Based Budgeting
A fundamentally different approach: instead of fixed percentages, every dollar of income is assigned a specific job based on your actual expenses, until income minus expenses equals zero. It takes more upfront setup than a percentage rule but adapts more precisely to irregular costs.
You Don’t Have to Pick Just One
One useful approach that doesn’t get talked about much: use a simpler rule like 70/20/10 as your day-to-day tracking system, and run the more detailed 50/30/20 breakdown periodically — say, once a quarter — as a diagnostic check.
The daily rule keeps budgeting low-effort. The periodic check-in catches problems the simpler rule can’t see on its own, since 70/20/10 won’t tell you if your needs specifically have crept up even while your total spending stays on target. This isn’t unique to these two rules, either — any simple, fixed-ratio rule can serve as your daily framework, with a more detailed breakdown run occasionally to catch drift in specific categories.
The Number That Matters More Than the Framework
Here’s the thing neither rule makes a fuss about: the savings rate — 20% in both of the most commonly compared rules — is what actually predicts long-term financial progress, not which framework you use to get there. 70/20/10’s rise in popularity has been driven largely by social and financial media, rather than a single named source the way 50/30/20 traces directly back to Elizabeth Warren and Amelia Warren Tyagi’s 2005 book, All Your Worth — but both rules land on the same savings target regardless of where they came from.
If you automate a 20% transfer to savings the day you’re paid, the choice between these frameworks becomes mostly about which one is easier for you to stick with — which is a legitimate reason to choose one over the other, just not the only thing that matters.
Frequently Asked Questions
What are some alternatives to the 50/30/20 budget rule?
The most commonly compared alternative is the 70/20/10 rule, which uses one spending category instead of two and adds a dedicated debt or giving category. Other named alternatives include the 30/30/40 rule, the 80/20 rule, the 60/40 rule, and zero-based budgeting, which abandons fixed percentages entirely.
Which is better, 50/30/20 or 70/20/10?
Neither is universally better — both allocate the same 20% to savings, and the real difference is how the remaining 80% is organized. 70/20/10 tends to fit better for high housing costs or aggressive debt payoff, while 50/30/20 gives more visibility into whether needs or wants specifically are the issue.
What is the difference between the 40/30/30 and 30/30/40 rules?
They’re most likely the same rule, referenced with the percentages in a different order. The commonly cited version, 30/30/40, allocates 30% to housing, 30% to other necessary costs, and 40% to combined savings and discretionary spending.
Is 70/20/10 better than 50/30/20 for paying off debt?
It can be, since 70/20/10 includes a dedicated 10% debt category rather than folding debt payments into a combined savings-and-debt category like 50/30/20 does. That said, either rule can be adjusted — shifting more of the 20% savings toward debt under 50/30/20 accomplishes something similar.
Conclusion
50/30/20 and 70/20/10 aren’t really competing philosophies — they’re the same underlying idea organized two different ways, and they land on the same savings target either way. The more useful question usually isn’t which rule is objectively better, but which one matches your actual living costs and how much category-by-category tracking you’re willing to do.
A few things worth taking from this comparison:
- If your needs consistently run over 50% of your income, 70/20/10’s single spending category may feel less punishing than forcing an artificial needs-versus-wants split.
- If you want visibility into whether needs or wants specifically are driving your budget, 50/30/20’s extra category is worth the added tracking effort.
- Whichever rule you pick, the 20% savings target is the part that matters most for long-term progress — treat the rest as a personal preference about tracking style, not a verdict on financial discipline.
For the full explanation of how to apply 50/30/20 to your own numbers, see how to calculate the 50/30/20 rule, and for a deeper look at whether the standard rule fits your specific income, see is the 50/30/20 rule realistic.
Disclaimer
This article is for general educational purposes only and does not constitute financial advice. The income figure and calculations shown are illustrative, based on national average data, and will not match your individual income, taxes, or expenses. Consider speaking with a licensed financial advisor before changing your budgeting approach.
Anjali Kaur is a finance writer specializing in personal finance, international tax, and financial planning for digital nomads, expats, and remote workers. She breaks down dense, high-stakes topics — the Foreign Earned Income Exclusion, totalization agreements, tax residency, and visa-linked tax breaks — into plain-language guides that help readers make confident decisions. Her approach is research-led and source-driven: every figure is dated, and she flags where rules vary or have recently changed. Anjali fact-checks her finance and tax coverage against primary sources such as the IRS, the SSA, and official government tax authorities. Connect with her on Facebook or read more of her work in the Finance section.