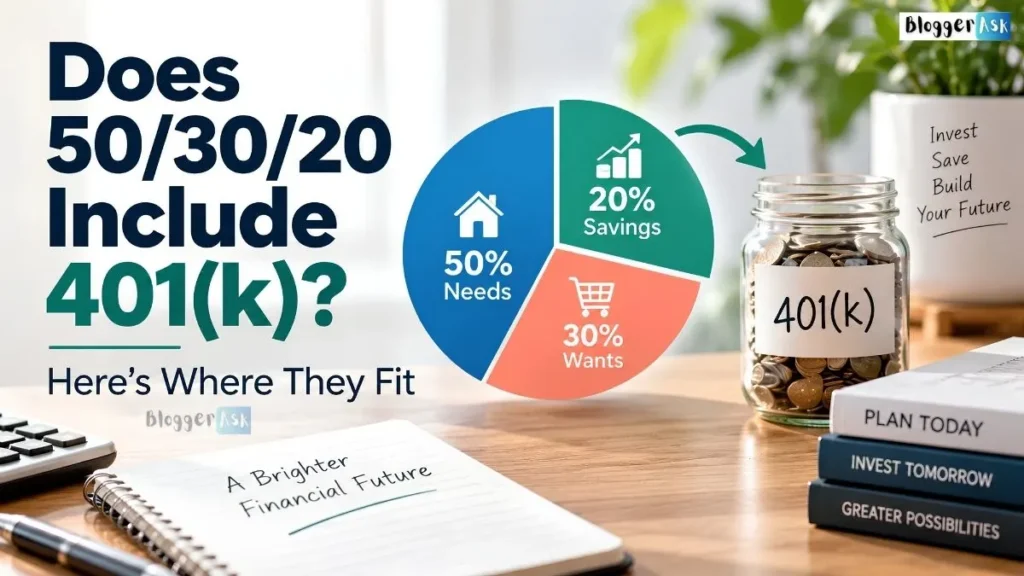
⚡ Quick Answer: Does 50/30/20 Include 401(k)?
Yes, under the budgeting method used in this guide, a 401(k) contribution counts toward your 20% savings category. This is a methodology decision this site applies consistently, not an IRS rule; other financial sources handle the timing differently, treating the contribution more like a payroll tax subtracted before the budget starts. Below: the calculation, an employer-match note, and what to do if your contribution alone is already 20% or more.
Key takeaways:
- Your 401(k) contribution goes in the 20% savings category — add it back into your income first if your paycheck already has it deducted.
- An employer match isn’t part of your personal 20% under this method, though it still boosts your real total retirement savings.
- A 401(k) contribution at or above 20% on its own means you’ve already hit the target — nothing more to add that month.
Does 50/30/20 Include 401(k)?
A 401(k) contribution belongs in the 20% savings category, alongside your emergency fund, other investments, and any extra debt payments beyond the minimum. It’s not a separate, fourth category, and it’s not excluded from your income before you calculate your budget.
Important: the 50/30/20 rule is a budgeting framework, not an IRS rule. The IRS sets contribution limits and tax treatment for your 401(k); this article explains how this site’s budgeting methodology categorizes those contributions once they’re made. Nothing below changes your plan’s actual rules — it’s a convention for organizing your own numbers.
Here’s the calculation:
Budgeting income = paycheck deposit + your 401(k) contribution
If your paycheck already has the 401(k) contribution deducted before it reaches your bank account, add that amount back in first — the same way this site’s guide to [how to calculate the 50/30/20 rule] handles other payroll deductions like health insurance. Once you have that fuller income figure, your 401(k) contribution is simply one line item inside your 20% target, not a cost that happened before the budget started.
Why Sources Disagree About This
If you’ve read more than one article on this topic, you’ve probably already noticed the disagreement. It comes down to a real, unresolved question: should a 401(k) contribution be treated like a tax (something removed before your budget even starts), or like a savings goal (something your 20% target is meant to cover)?
The “Treat It Like a Tax” Approach
Some sources take this position directly. New York Life’s guide to the 50/30/20 rule recommends treating 401(k) contributions “similar to taxes and Social Security” — part of what gets subtracted before you calculate your net income, rather than something counted inside your 20%.
The logic here is that a 401(k) contribution never touches your bank account, so treating it like a pre-existing deduction keeps your budget focused only on money you’ll actually see and spend.
The “Count It in Your 20%” Approach (This Site’s Method)
Other sources take the opposite position. Prudential’s budgeting guidance is direct about it: “If you automatically contribute to a 401(k) or other retirement account from your check, include it in the 20% savings category.”
This is the approach this site uses, consistently across all of its 50/30/20 content: a 401(k) contribution is a form of savings, not an unavoidable cost like a tax. Excluding it from the budget entirely hides how much real savings effort is actually happening.
Neither approach is factually wrong — they’re different conventions for organizing the same numbers. What matters is picking one and applying it consistently, so your savings rate means the same thing from month to month.
Does an Employer Match Count Toward Your 20%?
No, under the method used in this guide — and this is worth stating clearly, since it’s rarely addressed directly anywhere. The 20% target in this convention measures your own contribution, the money that comes out of your paycheck. An employer match is additional money on top, tracked separately rather than folded into your personal 20%.
That’s not a downside. Your actual retirement savings rate — yours plus your employer’s — is higher than your 50/30/20 numbers alone suggest. If you contribute 6% of your income and your employer matches half of that, your total retirement contribution rate is 9%, even though only the 6% you contributed counts toward your 20% target under this method. Keeping the two separate avoids two problems at once: understating your real total savings, and overstating what you’re personally responsible for maintaining if your employer’s match policy ever changes.
One related detail worth knowing: employer matches are often subject to a vesting schedule, meaning you may not fully own the matched funds until you’ve worked at the company for a set period. That doesn’t change how it factors into your 50/30/20 budget today, but it’s worth knowing before you count on that money as fully yours.
What If Your 401(k) Contribution Is More Than 20% on Its Own?
This happens more often than you’d think, especially if you’re contributing aggressively toward a match, catching up later in your career, or maximizing contributions in a high-income year. For 2026, the IRS allows employee 401(k) contributions up to $24,500, or $32,500 if you’re 50 or older.
If you’re between 60 and 63, a higher “super catch-up” limit of $11,250 applies instead of the standard $8,000, bringing your total contribution room to $35,750. For example, a plan participant earning $50,000 who was able to contribute the full $24,500 employee limit would be putting away roughly 49% of gross pay in retirement savings alone — far more than a 20% target on its own (actual eligibility depends on your plan’s rules and your compensation).
If this is your situation, here’s the short version: it’s not a problem to solve. If your 401(k) contribution already meets or exceeds your 20% target, you’ve hit your savings goal through retirement contributions alone. You don’t need to find additional money for an emergency fund or extra debt payments to “complete” the category — though building some liquid savings alongside a large 401(k) contribution is still worth considering, since retirement funds aren’t easily accessible in an emergency.
A quick way to check where you stand:
- Calculate your 20% savings target from your full after-tax income (401(k) added back in, per the method above).
- Compare that target to your actual 401(k) contribution alone.
- If the contribution already meets or exceeds the target, your savings category is complete for the month — extra debt payments or additional investing become optional, not required.
- If there’s room left, that’s what your emergency fund, extra debt payments, or other investing should fill.
Does It Matter If It’s a Roth or Traditional 401(k)?
Not for the 50/30/20 split itself — a Roth 401(k) contribution counts toward your 20% savings category exactly the same way a traditional 401(k) contribution does. The difference is in when you pay tax on the money, not in how it’s categorized for budgeting purposes.
Traditional 401(k) contributions are generally made on a pre-tax basis for federal (and usually state) income tax purposes — they reduce the income your income tax is calculated on. Roth 401(k) contributions are made with money you’ve already paid income tax on. Either way, both are still subject to Social Security and Medicare tax (FICA), and both are typically deducted from your paycheck before the remaining amount reaches your bank account. From a 50/30/20 standpoint, none of this changes which category the contribution belongs in — the tax treatment affects your overall tax bill, not your budget categorization.
One 2026 rule change worth knowing if you’re making catch-up contributions: if your prior-year wages from your plan sponsor exceeded $150,000, your age-based catch-up contributions must now be made on a Roth basis, regardless of whether your regular contributions are traditional or Roth. This doesn’t change how the money is categorized in your 50/30/20 budget, but it may affect your take-home pay differently than you’d expect if you were counting on the tax deduction from a traditional catch-up contribution.
A Worked Example
Here’s how this looks with real numbers. Say your paycheck deposits $4,200 a month after your 401(k) contribution is already taken out, and you’re contributing $300 a month to that 401(k).
| Step | Amount |
|---|---|
| Paycheck deposited (401(k) already subtracted) | $4,200 |
| 401(k) contribution (add this back in) | $300 |
| Income used for your 50/30/20 split | $4,500 |
| 20% savings target | $900 |
| Covered by your 401(k) contribution | $300 |
| Remaining savings target | $600 |
Your $300 401(k) contribution covers a third of your $900 savings target. In percentage-point terms, it’s already accounted for 6.7 of the 20 percentage points — leaving 13.3 percentage points, or $600, still to allocate toward an emergency fund, extra debt payments, or other investing.
Frequently Asked Questions
Does the 50/30/20 rule include 401k?
Yes. A 401(k) contribution counts toward the 20% savings category, alongside your emergency fund, other investments, and extra debt payments. Some sources instead treat it as a deduction similar to taxes, subtracted before the budget split — this site’s guide uses the “count it in your 20%” approach for consistency across all of its 50/30/20 content.
Does 401k count as savings in the 50/30/20 rule?
Yes, a 401(k) contribution is a legitimate form of savings and belongs in the 20% category rather than being excluded from your budget entirely.
Does an employer 401k match count toward my 20%?
No. Your 20% target reflects your own contribution only. An employer match is additional retirement savings on top of your personal rate, and it doesn’t count toward the 20% you’re responsible for maintaining.
What if my 401k contribution is more than 20% of my income?
That means you’ve already met your savings target through retirement contributions alone. You don’t need to add more to your savings category that month — any additional funds can go toward other goals or simply be treated as extra financial cushion.
Conclusion
A 401(k) contribution fits into the 50/30/20 rule as part of your 20% savings category — not as something to exclude before your budget starts, even though other sources handle this differently. What matters most is picking one convention and sticking with it, so your savings percentage means the same thing every time you check it.
A few things to take from this:
- Add your 401(k) contribution back into your income before calculating your 50/30/20 split, then count the contribution itself inside your 20% target.
- Track your employer match separately — it boosts your real retirement savings, but it isn’t part of your personal 20%.
- If your 401(k) contribution alone meets or exceeds your 20% target, that’s a sign you’re already hitting your savings goal, not a gap to fill.
📖 Continue Reading:
- Is the 50/30/20 Rule Realistic?
- How to Calculate the 50/30/20 Rule?
- What Is the 50/30/20 Rule?
- 50/30/20 Budget Examples
Disclaimer
This article is for general educational purposes only and does not constitute financial or tax advice. Contribution limits, vesting rules, and tax treatment can vary by employer plan and individual circumstances. Consider speaking with a licensed financial advisor or your plan administrator for guidance specific to your situation.
Anjali Kaur is a finance writer specializing in personal finance, international tax, and financial planning for digital nomads, expats, and remote workers. She breaks down dense, high-stakes topics — the Foreign Earned Income Exclusion, totalization agreements, tax residency, and visa-linked tax breaks — into plain-language guides that help readers make confident decisions. Her approach is research-led and source-driven: every figure is dated, and she flags where rules vary or have recently changed. Anjali fact-checks her finance and tax coverage against primary sources such as the IRS, the SSA, and official government tax authorities. Connect with her on Facebook or read more of her work in the Finance section.